Sum insured
The maximum amount the insurer will pay in a policy year.
Why it matters: Too low and a serious illness can exhaust it; too high and you may pay for cover you don’t need.
IRDAI-licensed insurance agent · I201102N0082050
Serving Delhi NCR: Gurgaon, Noida, Ghaziabad & moreWondering which health insurance plan is best — or which is the cheapest without being a trap? Health insurance is our specialisation: we help you compare cover, waiting periods, exclusions, network hospitals and claim terms, so you can choose with confidence.
Building a fuller safety net? We also guide on life insurance and general insurance — motor, home and travel.
Licence no. I201102N0082050.
You understand the policy before you decide.
Ask as many questions as you need.
One advisor for all three — health is our specialisation.
Start with the question you’re asking
Our 7-point check for choosing a plan that will actually pay when you need it.
Read the guide9 legitimate ways to pay less — and the cost-cutting traps to avoid.
Read the guide12 questions to ask, and how to verify an advisor’s IRDAI licence.
Read the guideA step-by-step checklist to compare plans beyond the premium.
Read the guideA quick decision guide for singles, families, parents, seniors and new parents.
Read the guideHow to size your cover and choose between term, savings and combination plans.
Read the guideSum assured, term, riders and how to compare claim settlement records.
Read the guideMotor, home, travel and personal accident cover — what each one actually protects.
Read the guideThird-party vs comprehensive, IDV and the add-ons worth paying for.
Read the guideWhere we help
We currently focus on individuals and families across the National Capital Region — by phone, WhatsApp and video call, so your exact location within NCR is rarely a constraint.
A human point of contact
Terms, limits and exclusions first — so the policy never surprises you later.
No scripts, no deadlines. Take the time your family needs.
Renewals, portability and claim-process guidance are part of the relationship.
What we cover
Health insurance is our specialisation. Explore the areas people ask about most — including life and general insurance — then get tailored guidance for your situation.
Understand coverage, waiting periods, exclusions and policy conditions for one person.
ExploreExplore family floater structures, sum insured and the details that matter for your family.
ExploreLearn about age, pre-existing conditions, co-payment and waiting periods before you decide.
ExploreUnderstand maternity benefits, waiting periods, newborn coverage and applicable conditions.
ExploreSize your cover, compare term vs savings-linked plans, and understand riders and claim settlement.
ExploreCar, home, travel and personal accident cover — third-party vs comprehensive, IDV and add-ons.
ExploreGet practical guidance on cashless claims, reimbursement, documents and policy renewals.
ExploreBuild your understanding of the terms and decisions behind health, life and general insurance policies.
ExploreFor every stage of life
Pick the stage that sounds most like you and see what is worth checking first.
Employer cover is useful, but it usually ends when the job does. A personal policy in your 20s or early 30s means waiting periods start counting early — long before you might need them.
A good question to ask: “What happens to my cover if I change jobs?”
Maternity benefits usually come with a waiting period, so the best time to plan is well before you need it. Newborn cover and vaccination benefits differ from product to product.
A good question to ask: “When exactly does maternity cover begin, and what is the limit?”
A family floater shares one sum insured across everyone, while individual policies give each person their own. The right structure depends on ages, health history and budget.
A good question to ask: “If one family member has a big claim, how much is left for the others?”
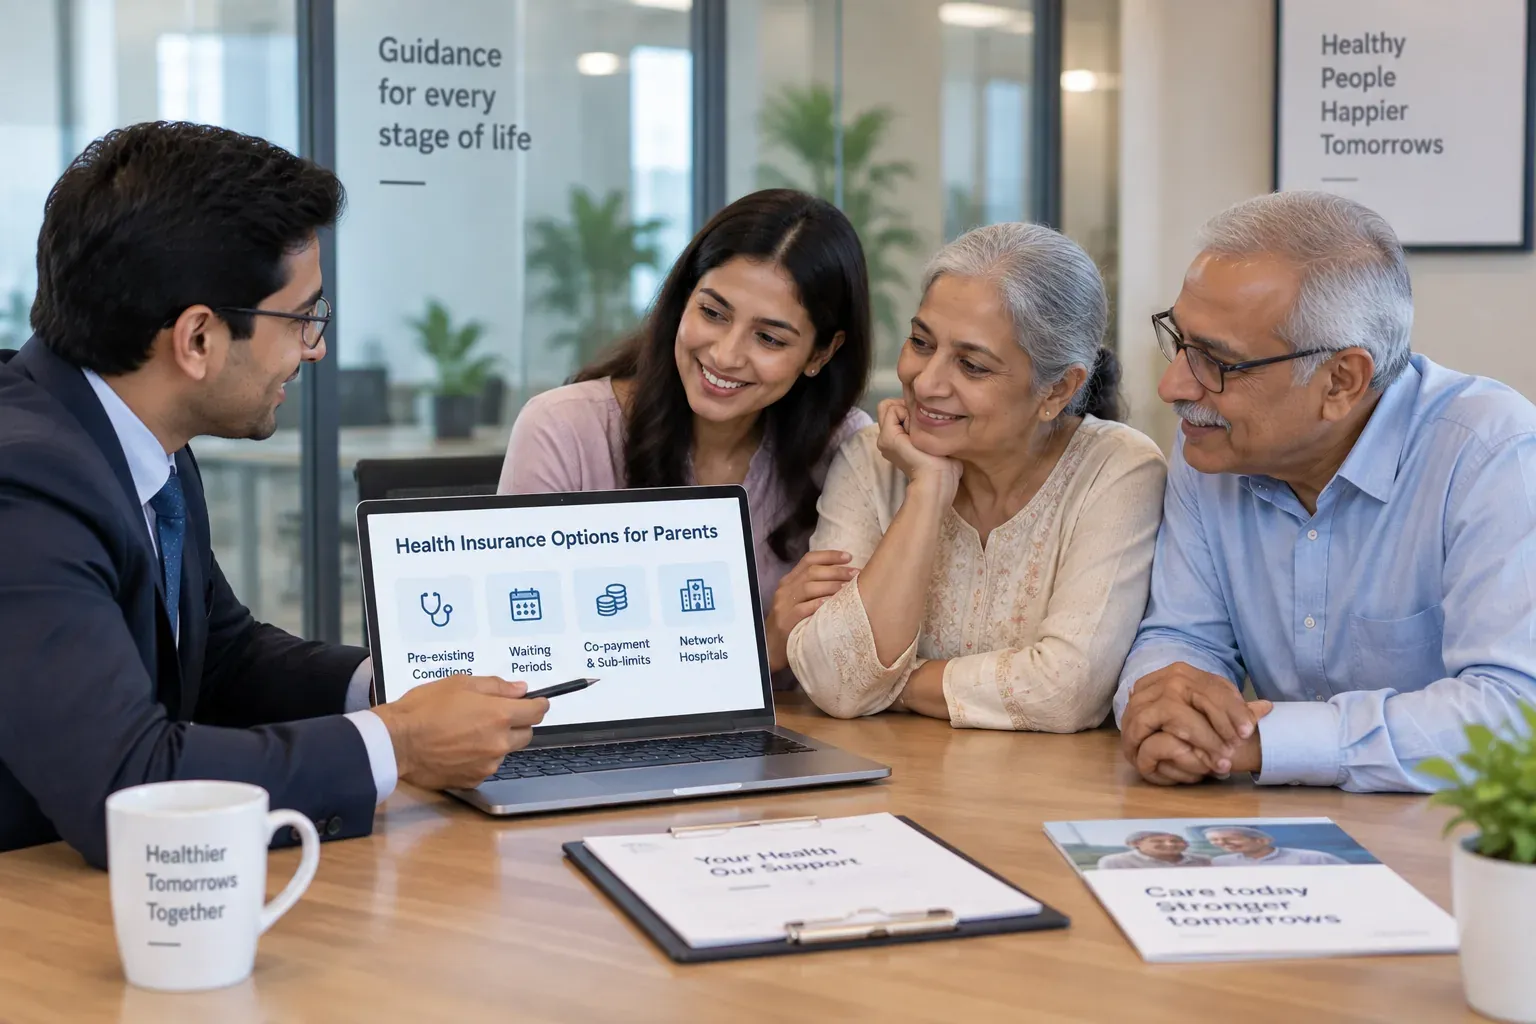
Parents often have existing conditions, which makes waiting periods, co-payment and sub-limits the most important parts of the policy — more than the headline sum insured.
A good question to ask: “Which conditions are covered from day one, and which after a waiting period?”
Make a considered decision
Share a few details and Amit Kumar can help you understand the factors worth considering. No pressure, no promise of a particular policy.
Prefer to talk now? +91 99583 88863 WhatsApp
Step 1 of 2
Start with the basics. You can share more when you speak with us.
Policy benefits, premiums, exclusions and eligibility vary by product and customer. Please refer to the applicable policy documents before purchasing.
Step 2 of 2
Amit Kumar will get in touch to understand your requirements and talk you through the factors worth considering.
Need to speak sooner? Call +91 99583 88863 or WhatsApp us.
A simpler way forward
Your family profile, age and requirements.
Relevant features, benefits and conditions.
Coverage, premium and waiting periods.
Assistance with the selected application.
Renewal and claim-process guidance.
Policy jargon, decoded
Most confusion comes from a handful of words. Here is what each one means — and why it matters.
The maximum amount the insurer will pay in a policy year.
Why it matters: Too low and a serious illness can exhaust it; too high and you may pay for cover you don’t need.
The time after buying when certain claims are not yet payable.
Why it matters: Pre-existing diseases, specific illnesses and maternity all have their own waiting periods.
A condition you had, or were advised treatment for, before buying the policy.
Why it matters: Declare it honestly. Hidden conditions are a common reason claims are disputed.
A percentage of every claim that you pay yourself.
Why it matters: Lowers the premium, but raises your share of every hospital bill.
A fixed amount you pay before the insurer starts paying.
Why it matters: Common in top-up plans — the deductible is usually your base cover.
A cap on the room category or daily rent the policy allows.
Why it matters: Choosing a costlier room can proportionately reduce other charges in some policies.
Lower caps on specific treatments or expenses within the sum insured.
Why it matters: A high sum insured can still have low limits for cataract, joint replacement and more.
Your sum insured is refilled if you use it up in a policy year.
Why it matters: Conditions apply — often for unrelated illnesses, so read the wording.
A reward, usually extra sum insured, for a claim-free year.
Why it matters: Can grow your cover over time without raising the premium.
A hospital that has a tie-up with the insurer for cashless treatment.
Why it matters: The best policy is less useful if no good hospital near you is on the list.
The option to move your policy to another insurer at renewal.
Why it matters: You can change insurers without losing accrued waiting-period credit, subject to conditions.
A period after which claims generally cannot be contested for past non-disclosure.
Why it matters: Ask how long it is and what exceptions apply.
Your pre-purchase checklist
Tick them off as you compare. If a few are unclear, that is exactly what a conversation with us is for.
Go through it with us0 of 10 checked
When you need support
Understand the general process for cashless and reimbursement claims, what documents may be requested, and when to inform the insurer or claims administrator.
Read the full claims guideThe hospital settles directly with the insurer or its claims administrator, subject to approval.
Confirm the hospital is on your insurer’s network list before admission.
For planned treatment, inform the insurer or claims administrator in advance. For emergencies, do it as soon as possible after admission.
The hospital submits the request. The insurer reviews it and confirms what it will pay.
At discharge, the final bill is reconciled. Non-payable items, if any, are paid by you.
You pay the hospital first, then submit the bills and documents to the insurer.
Let the insurer know about the hospitalisation within the time stated in your policy.
Collect bills, receipts, reports, prescriptions and the discharge summary in original.
File the claim form with documents, within the timeline in your policy wording.
The insurer assesses the claim as per policy terms and may ask for more documents.
The MyMark library
A clear starting point for first-time buyers.
Read guide Policy termsSee why timing can matter as much as coverage.
Read guide Making a choiceUnderstand the difference before comparing options.
Read guideQuestions people ask
Good insurance decisions begin with good questions. Find a few answers here, then ask us about your situation.
Ask your questionThere is no single best plan. The best health insurance plan is the one that fits your age, family, city and health history — with enough sum insured, short waiting periods, manageable co-payment and sub-limits, good cashless hospitals nearby and a reliable claims record. Compare plans on those points rather than on a ranking.
The cheapest plan is the one with the lowest total cost over time — premium plus what you pay at claim time — not simply the lowest premium. Buying early, choosing a floater, adding a super top-up and comparing co-payment and sub-limits can reduce cost without cutting the cover that matters.
Choose an IRDAI-licensed advisor who explains exclusions and waiting periods first, is open about how they are paid and which insurers they offer, and supports you at renewal and claim time. Ask for the licence number and verify it before sharing documents or paying.
No. A cheaper premium can mean higher co-payment, lower sub-limits, longer waiting periods or a smaller hospital network. Judge a plan on total cost and on how well it covers the treatments you are most likely to need.
Most policies cover hospitalisation costs — room rent, doctor fees, surgery, medicines and tests — and many include day-care procedures and expenses before and after hospitalisation. Benefits, limits and exclusions vary by product, so the policy wording is what counts.
It depends on your age, family size, city, health history and the cost of treatment where you live. A useful exercise is to imagine a serious hospitalisation in your city and ask what it would cost. We can walk through that with you before suggesting a range.
Yes. Many insurers offer plans for parents and senior citizens. Waiting periods for existing conditions, co-payment, sub-limits and premium vary widely, so it helps to compare them carefully. Many families choose a separate policy for parents.
In a cashless claim, treatment at a network hospital is settled directly between the hospital and the insurer or its claims administrator, subject to approval and policy terms. If you use a non-network hospital, you would normally pay first and claim reimbursement.
Portability generally lets you move to another insurer at renewal, subject to timelines and the new insurer’s underwriting. Accrued benefits such as waiting-period credit may carry over. Speak to us well before your renewal date.
Neither is universally better. A floater is often more economical for young families, while individual policies can suit families with older members or different needs. Our guide on floaters vs individual covers explains the trade-offs.
Yes. Always disclose pre-existing conditions accurately. Non-disclosure can lead to a claim being rejected or a policy being cancelled, and it is far easier to sort out before you buy than after you claim.
After you receive a new policy, insurers allow a short free-look window in which you can review it and return it if the terms are not acceptable. The exact period and refund terms are stated in the policy document.
Premiums may qualify for a deduction under Section 80D of the Income Tax Act, depending on your tax regime and circumstances. Please check with a tax professional for your situation.
Health insurance is our specialisation, but we also guide clients on life insurance (including term plans) and general insurance such as motor, home and travel cover. If you want to start with health and add other cover later, that is a common and sensible approach.
They protect against different risks and most people eventually need both: health insurance covers hospitalisation costs, while term insurance replaces your income for your family if you die. Neither substitutes for the other — we can help you prioritise based on your budget and life stage.
Yes, third-party motor insurance is legally compulsory for any vehicle used on Indian roads. Comprehensive cover, which also protects your own vehicle, is optional but widely recommended.
Your next question matters
Tell us what you are looking for and speak with an IRDAI-licensed insurance agent about the factors to consider.